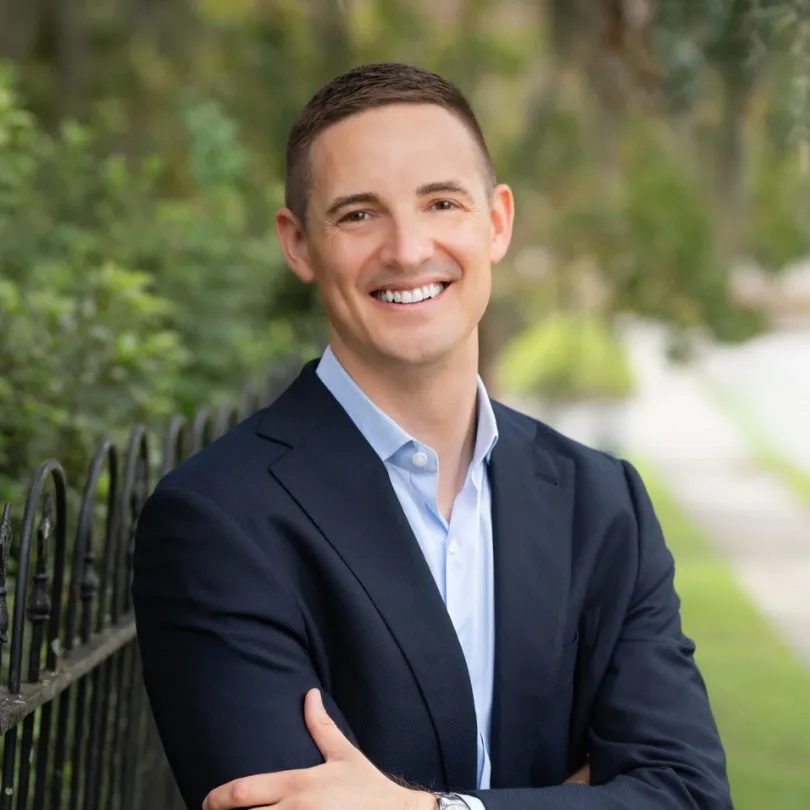
Joshua Hemmert, CFP®
Joshua Hemmert is a CFP® professional and the founder of Resettle Wealth, bringing more than 20 years of institutional retirement and investment experience to families making the turn from saving to spending.
When he is not working with clients, you will find him baking chocolate chip cookies with his kids or watching college basketball in March.
I started working at five in my parents’ donut shop in Dayton, Ohio, standing on a bucket so I could reach the register. They made my siblings and me save half of what we earned and taught us how to invest. But this was the late nineties. Watching the dot-com boom turn into a bust right as I started college was my first real lesson in market cycles.
I spent the next two decades at J.P. Morgan Asset Management in New York. As the lead U.S. investment specialist for income and retirement strategies, I helped launch a target-date series that now manages over $100 billion. My job was to know those portfolios cold and explain the markets to the advisors using them. For more than a decade, I also sat on The Clearing House investment committee, overseeing pension and 401(k) plans for hundreds of employees.
But I was always a step or two removed from the families whose money it actually was.
I started Resettle Wealth to sit on the other side of the table. I wanted to work with the same families year after year, through the stretch of life when the margin for error is gone. When you work with Resettle Wealth, you work directly with me. There is no junior team you get handed off to after the first meeting.
We moved from New York to South Carolina with our three kids to be closer to family. Today I work as a fee-only fiduciary serving clients nationwide. I’ve also written for Barron’s and 401(k) Specialist.
Explore More From This Author

How much income can we have in 2027 and keep the ACA subsidy?
In 2027 a married couple can have up to $86,560 of income and keep the ACA premium tax credit. Which accounts you spend from decides most of it.
Read InsightLet’s Find Out Where Your Retirement Stands
A 45-minute video call about your situation and the questions on your mind. There’s nothing to prepare, no cost and no obligation.